The Time Is Now – The Downfall of Pushing Off Investing [Post 1]

Updated: Nov 16, 2022
Who Should Read This
1. Young professionals who want to start investing.
2. Young professionals who have invested in the past but consider it a major flop.
(I’ve been there)
Why You Should Care
If your paycheck sits in the bank earning minimal interest, your dollars are actively losing value at average inflation rates.
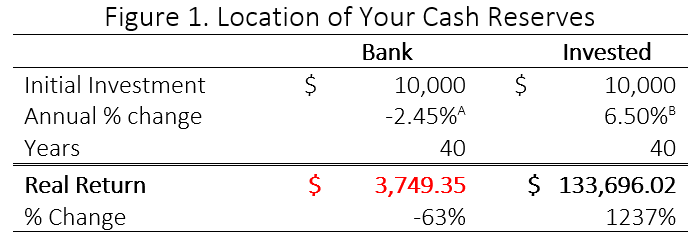
*Using monthly compounding
(A): (0.05% interest) - (2.5% annual inflation) = -2.45% return
(B): (9% annual return) - (2.5% inflation rate) = 6.50% return
As seen in Figure 1, leaving $10,000 in the Bank over 40 years is detrimental to overall financial well-being. While the funds may be gaining 0.05% of interest every year, the real returns are negative as an inflation rate of 2.5% squashes the measly bank interest return. Losing value in assets due to inflation is called purchasing power risk; this risk can be combated by seeking greater returns. The Invested column displays a brighter future involving an average stock market return.
When You Should Start
The best day to start was yesterday, making the 2nd best day to start, today. *On the contrary, current bear market conditions may make today a more enticing time to start than yesterday for rookie investors.
The Downfall of Waiting to Invest
You may think, “I don’t have the money right now” or “I’ll start when I’m __ years old.” For those earning a paycheck, here’s why TODAY is better than someday and why your 20s or 30s can be the decade to make millions.

In Figure 2, Investor A got a 10-year head start on Investor B. To make up for lost time, B made larger monthly contributions, so their total dollars invested over time were equal. What B failed to realize was the opportunity cost associated with missing out on 10 years of compound interest. Not gaining 9% on investment year over year is massive.
Investor A did everything identically to Investor B, but by starting 10 years earlier will have ~$2.26 million more than their colleague to enjoy in retirement.
Where and How Do I Get Started?
2 Ideas:
Taking advantage of any employer sponsored savings plans
Opening an individual online brokerage account to build a diversified ETF/Mutual Fund portfolio
While past performance is not an indicator of future results, the S&P 500 has annual returns of roughly 8-11% based on differing time frames; showing it doesn’t take an expert to receive steady returns over a long time period.
What’s the Catch?
There’s risk associated with investing. There will be many days, weeks, and months where your portfolio will tank to uncomfortable levels. Panic selling and veering away from a consistent investment strategy is typically harmful to your overall returns. Investing with long-term goals in mind and sticking to an evidence-based investment approach rewards the patient investor.
As the saying goes, time in the market beats timing the market. Start today, benefit tomorrow. Post 2 will outline how to set up and implement a passive investing strategy.


